VAT on garage work is not well served by the shortcut “labour at one rate, parts at another.” Revenue’s motor-repair guidance contains important exceptions, and tyres have their own explicit treatment. A workshop that builds one blanket rule into every job can produce neat invoices that are consistently wrong.
This guide summarises the current published rules that are most relevant to Irish repair workshops. It is not tax advice. Confirm your garage’s VAT configuration and unusual transactions with an accountant or tax adviser.
Current Irish VAT rates
Revenue’s current VAT rates show a standard rate of 23% and a reduced rate of 13.5% from 1 January 2026.
The rate is determined by the supply, not by whichever department entered the line. A part fitted during a repair is not automatically reduced-rated, and a service description does not override an item that Revenue specifically excludes.
Motor-vehicle repair services
Revenue lists certain motor-vehicle repair and related services at the reduced rate. The same entry identifies exclusions, including:
- mirrors
- batteries
- media players
- tyres
- tyre flaps
Revenue says these excluded items remain standard-rated when supplied in a repair service. The official entry also notes that the two-thirds rule does not apply to bona fide car repair and maintenance services under the stated concession.
Read the current wording in Revenue’s motor-vehicle repairs VAT entry. This is a better source than a rate table copied from an old invoice template.
Do not infer the treatment of every part
The Revenue entry gives examples of exclusions, not a complete workshop catalogue. When a product or transaction does not fit an established treatment, ask your accountant to decide it and then configure that item consistently.
A useful parts catalogue therefore stores a default VAT rate but allows an authorised user to review it. The default saves time; the review prevents convenience becoming policy.
Tyres and puncture repairs
Revenue’s motor-vehicle tyres VAT entry is explicit:
- supplying and fitting tyres as part of repair or maintenance is standard-rated
- a tyre or puncture-repair service is reduced-rated
- supplying and fitting a new tube as part of that repair is standard-rated
That can place different rates on one customer visit. The invoice should preserve the distinction at line level rather than hiding the work in a single description such as “tyre job.”
VAT registration thresholds
Revenue’s current VAT registration thresholds include:
- €42,500 for a person supplying services only
- €85,000 for a person supplying goods
- €85,000 for a person supplying goods and services where 90% or more of turnover comes from qualifying supplies of goods
Revenue calculates the threshold using turnover excluding VAT in a calendar year, subject to the inclusions and exclusions described in its guidance.
A garage normally supplies a mixture of labour and goods. Do not choose the higher threshold simply because parts appear on most invoices. The 90% test and the precise nature of the supplies matter. An accountant should confirm the applicable threshold and the date on which registration is required.
Businesses below the relevant threshold may elect to register, but that decision affects pricing, input VAT recovery and administration. It deserves advice based on the actual numbers rather than a generic rule.
What a VAT invoice needs to show
Revenue requires a VAT invoice to include specific information. The current list includes:
- the issue date and a unique sequential number
- the supplier’s full name, address and VAT registration number
- the customer’s full name and address
- the quantity and nature of goods or extent and nature of services
- VAT-exclusive unit prices
- discounts or reductions not included in the unit price
- the consideration exclusive of VAT for each rate
- the VAT rate or rates and total VAT payable
- the supply date where it differs from the issue date
Some transactions require additional wording or identifiers. Use Revenue’s complete VAT invoice information requirements, not this summary, as the authority.
For a workshop, clear line descriptions help both compliance and customer understanding. “Replace front brake pads” is more useful than “parts and labour,” particularly where different VAT rates or a later dispute are involved.
Our garage invoicing requirements guide covers the document and customer-authorisation workflow in more detail.
Correcting an issued invoice
Changing the stored total after an invoice has been issued can break the link between the customer’s document, the sales ledger and the VAT return.
Revenue’s guidance on amending a VAT invoice says:
- a price increase requires a supplementary invoice containing the increase and related VAT details
- a price reduction requires a credit note
- correcting an excessive VAT amount requires a credit note and revised invoice
- correcting an insufficient VAT amount requires a credit note for the full invoice and a revised invoice
A VAT credit note has its own required information, including a unique number, the reason for issue, a cross-reference to the original invoice, amended consideration, relevant VAT rates and tax amount. Revenue publishes the full credit-note requirements.
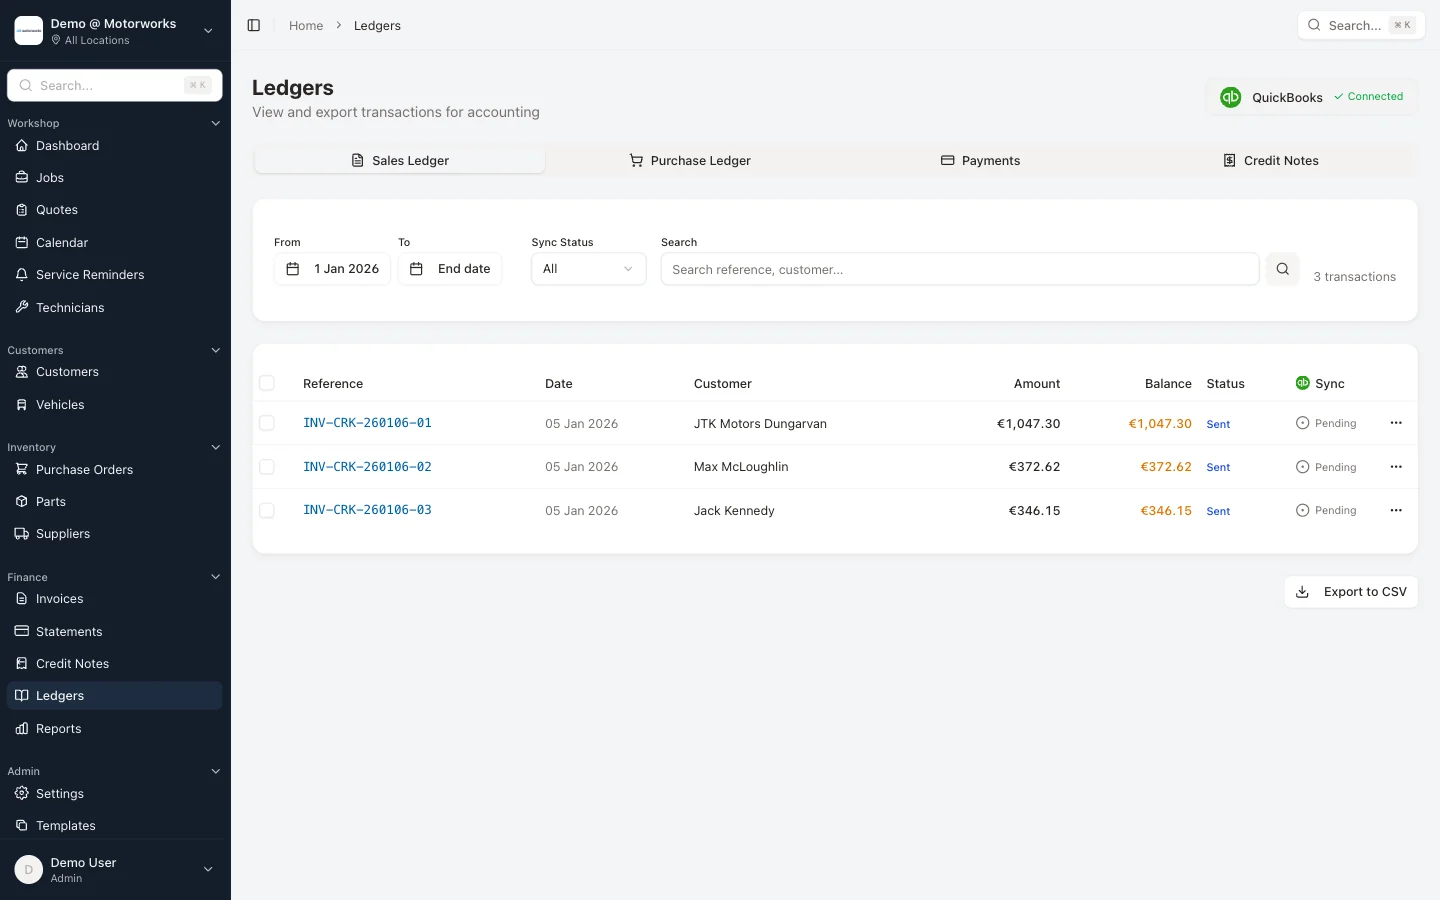
Motorworks keeps credit notes and customer statements connected to the underlying account record. The tax decision still belongs with the business and its adviser.
Keep the VAT evidence, not only the VAT total
Revenue says VAT-registered businesses need full and true records of VAT-related transactions. The supporting set may include invoices, credit notes, debit notes, receipts, cash-register records, vouchers, accounts and bank statements. Records must be detailed and current enough for Revenue to verify each transaction.
For a garage, a period-end VAT number should be supported by:
- issued sales invoices grouped by VAT rate
- sales credit notes and invoice corrections
- supplier invoices supporting input VAT claims
- payment records and bank reconciliation
- clear treatment of deposits, refunds and bad-debt adjustments where applicable
- a record of any manual VAT overrides and who approved them
The Revenue record-keeping guide for garages explains how the operational and accounting records fit together.
Configure rates at the right level
A workshop system should support VAT at line level. Useful controls include:
- default rates on labour codes and catalogue items
- a separate default for tyres and other known exceptions
- permission-controlled overrides
- VAT-exclusive and VAT-inclusive totals shown consistently
- reports grouped by rate and document type
- credit notes linked to the original invoice
Defaults should reflect advice agreed for that garage. A software vendor should not silently decide the tax treatment of a new item from its description.
Motorworks supports configurable line-level VAT, Irish tyre-levy records, invoice and credit-note documents, and VAT reporting. Book a demo to see how a mixed workshop invoice moves from job card to final document.
A VAT review checklist for garages
Before passing period figures to the accountant, check that:
- every completed taxable job that should be invoiced has been invoiced
- rates on tyres and other exceptions have been reviewed
- manual rate changes have a clear reason
- invoice and credit-note sequences are accounted for
- supplier invoices are attached to the correct supplier and period
- payments do not replace or erase the underlying invoice record
- the VAT report agrees with the document totals
- unusual transactions have been raised with the accountant
The aim is not to make reception staff into tax specialists. It is to make exceptions visible to the person who is qualified to decide them.
Official sources
- Revenue: Current VAT rates
- Revenue: Motor-vehicle repairs
- Revenue: Motor-vehicle tyres
- Revenue: VAT registration thresholds
- Revenue: VAT invoice requirements
- Revenue: Correcting a VAT invoice
Reviewed against the linked official guidance on 2 September 2026. VAT rules and rates can change. Confirm the treatment of your supplies with a qualified adviser.